Monday, November 9, 2026

HungryPanda murder: The gig economy must be strongly regulated and its workers protected.

Written by: Nick G. on 10 November 2026


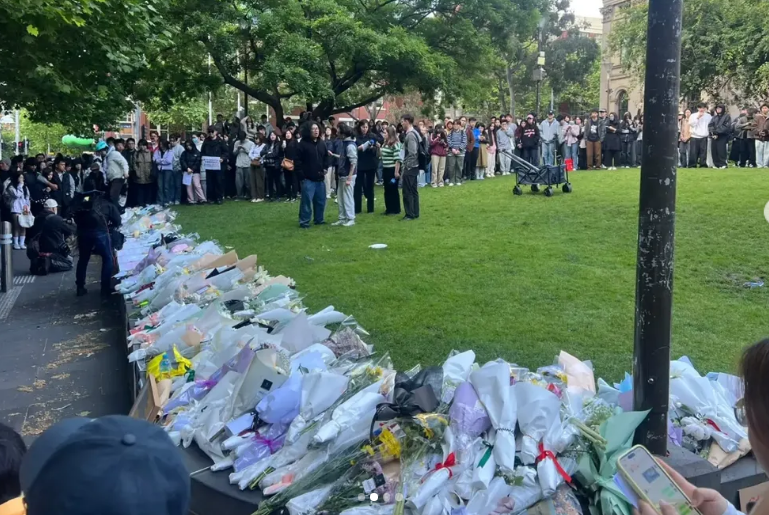
(Above: Hundreds attended the rally for Feng Jianming.  Source: Instagram)

The murder of HungryPanda delivery rider, and serious wounding of another, has again raised questions about both the vulnerability of delivery riders to personal danger, and the inadequacy of mental health services.

In February, we covered the case of HungryPanda delivery riders who were taking strike action in Sydney over wages and conditions. There were allegations that Chinese police had intimidated the families of some of the delivery riders back home in China. Our article included extensive details of the ownership of HungryPanda and the role of international finance capital in its ownership and organisation.

Feng Jianming, 54, was stabbed to death by 51-year old Robert Urbano following his interference with the bikes the two delivery riders had left outside a Melbourne restaurant.  They intervened to stop damage to their bikes when Urbano turned on them with his knife.

Urbano has now appeared in court to face charges relating to the death and injury. The court was hearing details of Urbano’s schizophrenia diagnosis when he stood on a chair in his holding room, pulled his pants down and exposed himself to the camera.

Urbano’s mental health is symptomatic of the lack of support for persons who require professional health and psychiatric support. His actions come in the wake of the attack on Helen Haines MP. In our article on that event, we accused the government of gutting mental health services and echoed criticisms by 2010 Australian of the Year Professor Pat McGorry:

Even if the tooth fairy could wave a magic wand over the empty heads in government and opposition benches and see a release of needed funding, the fundamental approach to mental health under capitalism will not improve.

The ethics of bourgeois psychology upon which mental health services rest, treats patients at the crisis stage. As McGorry said, it is the “ambulance at the bottom of the cliff” approach which has been allowed to develop through the absence of preventative approaches which could have prevented the reaching of the critical stages.  

It deals with crises as the failings of the individual and as the personal problem of the individual, rather than as the failings of capitalist society and the social problems of the system as a whole.

The answer is not to institutionalise those with manageable mental health problems, but to ensure they have professional support, preferably within the families and communities in which they live.

No doubt chastened by the controversy over the February 2026 HungryPanda delivery riders’ strike, HungryPanda has promised to arrange visas and travel for Feng’s family to come to Australia for his funeral.

The company has been accused by its workers of fining them if the delivery is lost or stolen, forcing them to compromise their safety to protect company profits.  They are forced to get to their destinations as quickly as possible in order to make enough money for themselves, and more for the company. The whole gig economy is a ruthless frontline of capitalist exploitation.

Meantime, there has been an outpouring of support from all sections of the community for Feng, including a large and emotional rally outside the State Library last Saturday night, and an online fundraiser for Feng’s family which has exceeded $420,000 in donations. 

State and city authorities have lived up to Professor McGorry’s criticism of capitalism’s “ambulance at the bottom of the cliff” approach.

Victorian Premier Ben Carroll has vowed to make "whatever changes are necessary" following Feng’s fatal stabbing and Melbourne Lord Mayor Nick Reece, who attended the vigil, said he had spoken with HungryPanda management and offered to hold a roundtable to discuss safety conditions for delivery riders in the city.

They must be held to these offers, and the actions should include a discussion of community mental health services as well as matters relating to traffic management and pressures on delivery workers to meet management demands on schedules and efficiency.


Sunday, November 8, 2026

Osborne Shipyard AUKUS Nuclear Submarines - Are They "Done and Dusted"?

Written by: Ned K. on 9 November 2026


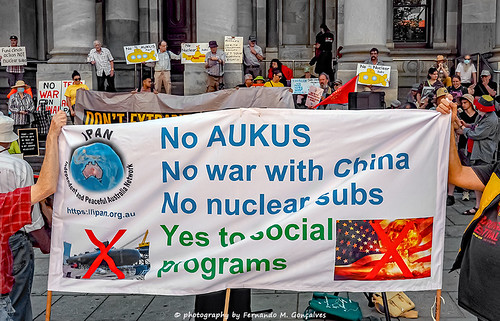
(Adelaide rally against AUKUS.  Photo supplied Fernando Goncalves)

The findings of the public inquiry into AUKUS were announced by former ALP Minister Peter Garrett at the National Press Club last week, with the question "Will AUKUS keep us safe - and at what cost?"

There was scant coverage of this in the mainstream media and not a single word about it in the Murdoch daily mass distribution newspapers of the major capital cities. This is not surprising. However, there are signs that sections of big business in Australia who support the US -Australia Alliance are having real doubts about the AUKUS nuclear submarine agreement and building of nuclear submarines at the Osborne shipyard near Port Adelaide.

The big businesses having doubts include the Murdoch empire itself. They are not concerned about the people of Osborne and Port Adelaide and Adelaide itself becoming a nuclear target. Nor are they concerned about the danger of nuclear waste and where to store it. Their concern is that rapid changes in military technologies are going to make nuclear powered submarines obsolete, both in the event of war between the US and China and for defending big business interests in Australia.

"Drone and Dusted"

Hidden away in the "Commentary" page of Murdoch Press's "The Australian" (Wednesday 4th November) was an article "Is AUKUS Drone and Dusted" by columnist Robert Gottleiebsen.

His article starts off sounding the alarm for his big business reader audience.

"Potentially, the most serious black hole in Australian government spending is AUKUS.

"Back in 2021, the AUKUS submarine agreement made sense for all three parties - the US, UK and Australia. But dramatic changes in warfare technology are making the deal increasingly dangerous for Australia and potentially less relevant to our partners. Yet we continue to spend as though nothing has changed."

The article goes on to say that nuclear-powered submarines were meant to be able to travel through deep sea waters undetected. This is what the champions of AUKUS including the likes of Morrison, Albanese, Wong and Marles continue to say makes the nuclear-powered submarines in "the national interest". 
Gottliebsen's article argues that "detection technology and artificial intelligence are potentially transforming the ability to locate and destroy older-technology submarines."

The solution put forward by this Murdoch Press article is not that the Australian government’s full support for the USA in preparing for war with China should be withdrawn. The solution proposed is that Australia contribute to the US war machine by developing "both offensive drone capabilities and effective systems for defending against drone attacks".

The Murdoch Press article also doubts that the UK has the technological capability and political certainty to provide the submarine design for Australian built submarines in the 2030s. Gottliebsen's article concludes that the shipyard being built at Osborne for yet to be designed UK nuclear submarines is looking more likely to be a wasteland of large empty buildings and destroyed natural environment.

The multinational corporations with direct economic interests in the nuclear submarine construction in Australia will not worry too much if the nuclear submarines are obsolete when or before they are completed. They have already sucked in compliant politicians at federal and state level to this profit-making project and promised a rosy career future for young people at the Osborne shipyard itself and its dependent businesses.

This is the price of servility by governments to AUKUS and the servility to big imperialist powers.

Local Osborne people and people of Australia deserve better than this.


Thursday, November 5, 2026

This social system must go!

 Written by: Nick G. on 6 November 2026


In 1859, Karl Marx wrote “There must be something rotten in the very core of a social system which increases its wealth without diminishing its misery…”

That social system was and is capitalism, and nothing much has changed in the more than 160 years since Marx’s observation.

Private wealth in Australia has increased rapidly in recent times, as has the misery inflicted on working people.

The fifth interest rate increase this year announced by the Reserve Bank takes interest rates to an 18-year high. The decision is callously intended to drive up unemployment and to put further spending pressures on mortgage holders and renters, already struggling with day-to-day living expenses. The interest rate rise means that there will be more unemployed and under-employed, more homeless families, and more people with or without jobs lining up at food charities. 

Reserve Bank governor Michele Bullock knows this and makes no apology.

She also knows that the number of ultra-wealthy Australians (those with net worth over US$30 million) is climbing rapidly. Ultra-high-net-worth households grew to 16,640 in 2026, a one-third increase since 2021. Australian billionaires grew even faster, surging 77% from 48 to 85 over the same period, the fourth-fastest rate globally.

High-net-worth households (those with wealth exceeding $1 million) grew from 1.21 million to 1.33 million, with their investable wealth rising 8% to $4.6 trillion.

The Australian Council of Trade Unions offered a converter which allows wage-earners to see how their earnings compared to those of Australian billionaires:

Let's say your annual wage is $80,000 (38 hours per week over 52 weeks).

The average Australian billionaire?

They make that in 4 hours 51 minutes. You need a whole year – they need a morning.

Wanna know how long you'd have to work to make what the billionaire makes in one year?

1,803 years. Clock on in 223 AD, never take a day off, and you’d just about get there by now.

Noone is telling those millionaires and billionaires at the height of the capitalist class that they must reduce their earnings, cut their investments, stop paying for luxuries.

But the government is told to cut its spending, and will only do so where the interests of the rich will not be touched. The government’s “savings” will come from the people.

Europe is currently ablaze with the anger of the working class and the youth. They face the same problems as Australian workers and youth: inflation, interest rate rises, homelessness, high rents, poor education and health services.

New Zealand is on the eve of an election – too close to call – but where people are facing the same problems as their Australian cousins, and their government is the equivalent of the Australian Liberal and National Opposition.

It doesn’t matter what choice of colours the governing parties of capitalism garb themselves in, the rich will increase their wealth at the expense of the increasing misery felt by the rest of us.

Rather than playing parliamentary games, growing struggles in workplaces and communities will increasingly point in the direction of socialism as the only answer to capitalism. 

Monday, November 2, 2026

US pushes QUAD to counter China’s southern diplomacy

 Written by: (Contributed) on 3 November 2026


The surprise meeting scheduled for QUAD representatives on the sidelines of the forthcoming ASEAN and East Asia summits in mid-November would tend to indicate reassessments of the regional balance of forces have raised concerns. A formal agenda for the high-level diplomatic meeting is set to be finalised in late October. It is not coincidental that the meetings will take place in Manila; the Philippines retains a central position for US regional diplomacy, 'US interests' and a series of nine sensitive military facilities, largely in the north of the country, facing various areas of tension.

An announcement that QUAD leaders would be meeting in Manila during mid-November was met with surprise; the US-led regional defence and security body had lain virtually dormant for the last three years. (1) The QUAD was established in order to present a challenge to China in the Indo-Pacific region. It was rested upon a Pentagon updated Indo-Pacific Strategy (IPS) in which the Philippines had a central geo-political and strategic position. (2) It also included the upgrading of the US-Japan alliance into the status of a global alliance. (3)

Calls for Australia to strengthen its diplomatic links with Japan are, therefore, best assessed in that light: in what has been described by Canberra as 'the deteriorating regional and global environment, raising concerns over the reliability of the historic US security guarantee'. (4) Australia has, historically, been a southern hub for US regional interests; Japan has been its northern counterpart. The US has thrust greater responsibilities on both.

The announcement also coincided with a report from the International Monetary Fund (IMF), that global economic growth is slowing; while it reached 3.5 per cent last year, it is now set to drop to 3.1 per cent. (5) The report also warned that if the US-Iran war continued for longer that 'global growth will be significantly lower and inflation much hotter'. (6) With the Middle East entering into a period of prolonged turmoil, the war has shown no sign of ending in the foreseeable future. Fuel prices have already escalated; and will do so still further.

Despite the US-led global economic uncertainty, however, countries associated with the regional ASEAN have developed stronger links with China, raising further diplomatic concerns over related factors and considerations. China, for example, has been ASEAN's leading trading partner since 2009, and ASEAN's largest since 2019. (7)
In recent times it had strengthened trade links still further: last year ASEAN recorded China's trade had increased by 7.4 per cent over the previous year; in the period January-July 2026, total trade had reached US$744 bn, an increase of 24.7 per cent over the same period for 2025. (8) The forthcoming QUAD diplomatic meeting, therefore, is best assessed in that light, with other related factors and considerations.

It is particularly important to assess the significance of China's diplomatic relations with specific ASEAN countries and how trade considerations have merged with other factors.

Cambodia has provided a good vantage point to highlight the predicament confronting the QUAD, and the rapidly changing balance of forces.  

Cambodia, historically, part of French-controlled Indo-China, has had a troubled and traumatic and poverty-stricken history. After joining ASEAN in 1999, however, China responded with financing 132 joint projects in the following fifteen years. (9) They formed the basis of longer-term diplomatic co-operation. In April this year, for example, an official diplomatic note announced the two countries would 'deepen strategic relations'. (10)

The diplomatic initiatives also included China fostering closer relations with neighbouring Vietnam, also a former part of Indo-China, with troubled relations with Cambodia. Vietnam, furthermore, previously opted to join the US’s Indo-Pacific Strategy alongside the ROK, Singapore, Taiwan and others. (11) Vietnam's diplomatic relations with the US now appear to have become problematic and far from straightforward.

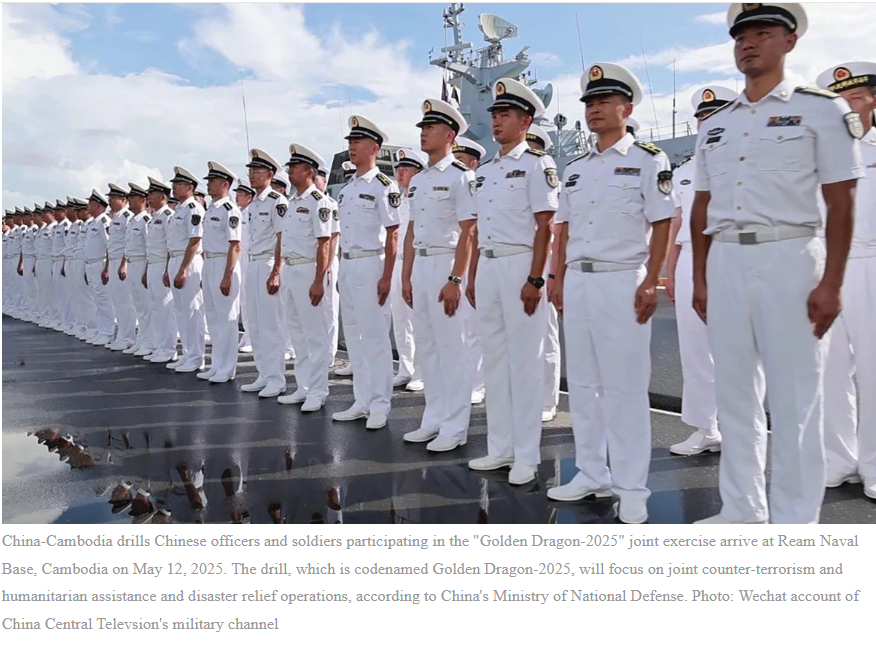
While China's deepening diplomatic links with the region have included the Ream joint naval facility in Cambodia and the Ban Keun joint air force base in Laos, Beijing's relations with Vietnam have correspondingly challenged their role inside the IPS. (12) Washington and the Pentagon appear to have failed in recruiting Vietnam into the IPS as a potential stalking horse to serve 'US interests'.    

A statement from Canberra about China's diplomacy toward Laos and the Ban Keun base noted it was a 'clear win for China … and a security concern for the US'. (13)

Meanwhile an official media release from the Philippine government noted the close relations between China and Cambodia 'fuel suspicions' for the US. (14) The Pentagon, moreover, has assessed the Ream Naval Base as 'a strategic military outpost'. (15)

The Ream Naval Base has been perceived by policymakers in Washington, DC, primarily as a threat to regional security within the broader strategic rivalry outlined in the 2018 US National Defense Strategy, which accuses China of leveraging military modernization to reshape the Indo-Pacific region to its advantage.

It is also not coincidental that the diplomatic statements were issued from Manila; the nine military facilities under US control are clearly used for regional intelligence-gathering. While their main focus, previously, were the more problematic areas of the region, including the Taiwan Straits and Korean Peninsula, recent developments in Cambodia and Vietnam appear to indicate a clearly visible changing regional balance of forces away from traditional hegemonic positions enjoyed by Washington and the Pentagon.

   
1.     Quad leaders find a Manila envelope, Australian, 22 October 2026.
2.     The reasons behind Washington's push for GSOMIA., (Diagram), Hankyoreh, 12 November 2019.
3.     Ibid.
4.     'Grand bargain': The case for a Japan treaty, Australian, 15 October 2026; and,         Study: US no longer dominant power in the Pacific, Information Clearing House, 22 August 2029.
5.     Global growth stalling, warns IMF., Australian, 14 October 2026.
6.     Ibid.
7.     Official websites: ASEAN; and, Towards and Equal Partnership, East Asia Forum,  Vol. 15, No. 3, September 2023, pp. 3-5; and, Japan as a diplomatic asset to ASEAN, ibid., pp. 6-8.
8.     ASEAN, ibid.
9.     Wikipedia: Cambodia-China Relations.
10.   Cambodia, China upgrade 2+2 dialogue to 3+3, The Asia News Network, 24 April 2026.
11.   Hankyoreh, op.cit., 12 November 2019.
12.   China's first foreign military air base, Australian, 15 October 2026; and, Vietnam and China get closer, The Guardian, 4 May 2026.  
13.   Australian, ibid., 15 October 2026.
14.   China's foreign, defence ministers, The Manila Bulletin, 23 April 2026.
15.   Ibid.


Thursday, October 29, 2026

Capitalist credit Pt 2: Their word is your bond

 Written by: Nick G. on 30 October 2026
 

The bond market is not as prominent in most people’s lives as the share market.

Private companies and government can raise capital by issuing bonds which operate as IOUs. They are generally regarded as a safer investment than shares because they are issued with a definite rate of interest. 

Unlike shares, their value does not rise or fall.  What you pay, you will eventually get back. (Unless you choose to sell them, in which case you may either make a loss or a gain.) Like shares, the interest paid to bond-holders can only be derived from the surplus value created by workers’ labour power. In the case of government bonds, the government appropriates part of that surplus value through corporate and personal income taxation as well as from various fees and fines.

Bonds represent a loan from the investor to the issuer with the latter promising to repay any borrowed money, along with a set amount of interest. That promise, their word, is the guarantee of the bond’s value to the investor. Because they are regarded as safe and secure, bonds are also called securities.

Can the bond market collapse?

Safety and security are, of course, relative under capitalism. A bond market, just like a stock market, can collapse if the conditions are right. A collapse of the bond market would occur if confidence in bonds deteriorated so severely that investors rushed to sell, buyers became scarce, borrowing costs surged, and the financial system struggled to absorb the losses.

On October 9, Yahoo Finance warned of a global bond market “meltdown”, saying:

For the past month, global bond markets have been in the grips of a historic sell-off triggered by a tangle of complex economic issues ranging from the ongoing war in Iran to rising deficits to the race to build out data centers to power artificial intelligence.

Among the “tangle of complex economic issues”, Government debt can be a major cause of bond market instability. Governments, like the US, that continually run large budget deficits must issue new bonds to finance spending and refinance maturing debt. If investors begin to doubt a government's ability or willingness to service its obligations, they may demand much higher interest rates or refuse to buy its bonds.

If there is a sudden surge in interest rates, new bonds will offer higher yields than old bonds at a lower fixed interest rate, and investors holding them will find them less attractive and may seek to sell them below their value.

Two recent examples of bond market crashes occurred in the US in March 2020 and the UK in September-October 2022. In the US case, investors spooked by the Covid-19 pandemic rushed to sell US Treasury securities, normally regarded as among the world's safest assets, in return for cash. The Federal Reserve intervened on a very large scale to support the functioning of the bond market.

In the UK case, a change in government fiscal policy led to a massive sale of UK government bonds requiring intervention by the bank of England to reverse the collapse.

The global bond market is usually larger than the global share market, so its collapse could have more severe consequences for global capitalism. However, recent data suggests that there has been something of a reversal: the total value of contemporary global stock markets is approximately $160–165 trillion, while the global bond market is approximately $109 trillion. Perhaps one of the reasons for the surge of speculative capital into the share markets is the spate of IPOs launched by AI companies. Musk’s SpaceX in June 2026 was the largest ever IPO, at a valuation of US$1.77 trillion, making Musk the world’s first trillionaire. Anthropic’s forthcoming IPO is predicted to surpass SpaceX as the biggest capital market fundraising in history. The bubble is getting bigger…

How does the US dollar, as a fiat currency, sustain the US debt?

A fiat currency is one that is not convertible into a fixed quantity of gold or any other commodity. The US dollar has been a fiat currency since August 1971. Being a fiat currency means that the US Treasury can create as many dollars as it wishes, and use those to pay interest on Treasury bonds, and to pay back their cost when they mature.

The US Treasury can both issue bonds to access investors’ capital, drawing on the US dollar foreign reserves of other governments and international investors, and create the money to service the bond. But creating extra dollars does not of itself create extra value. That can only be done by the productive use of capital when it is utilising the labour power of employed workers. 

Government bonds are therefore a form of interest-bearing fictitious capital: they represent a transferable claim on the government’s future income derived from surplus value and obtained through taxes and other imposts.

While the US Treasury can create new dollars, it cannot do this indefinitely without causing inflation, interest rate rises and currency devaluation. The US dollar can sustain US debt but not forever.

China and US Treasury bonds

The market for US Treasury bonds is a potential source of crisis because the US dollar is the basis of international finance.  The issuing of US Treasury bonds keeps the US in debt to global investors. The central question is therefore not simply how much debt the US government has accumulated, but whether investors remain willing to finance that debt, at what interest rate, and whether the financial system can withstand a sudden change in confidence.

A complicating factor is the Chinese purchase of US Treasury bonds.

The US anxiety over China’s financing of the US deficit was revealed in 2010 when Australian PM Rudd met with US Secretary of State Hillary Clinton. Rudd advised Clinton to accept a Chinese presence on the world stage but to keep force as a back-up, and Clinton became exasperated and asked “How do you deal toughly with your banker?”

Within three years, China had reached the peak of its holdings of US Treasury bonds.  They were estimated to be worth $1.3 trillion in 2013. The figure has gone down since as China seeks to diversify its holdings and to use the yuan and the rouble in trade with the Russian Federation. As of August 2026, China held approximately $590.7 billion in U.S. Treasury securities.

China has no plans to plunge bond markets into a crisis for anti-hegemonic purposes

There are some on the Left who believe that China is divesting itself of US Treasury bonds to create difficulties for the US dollar in anticipation of making the yuan the currency of international trade.

This view is particularly held by those who maintain that social-imperialist China is still a socialist country, and that its divesting itself of US Treasury bonds is a progressive anti-hegemonic struggle. 

An actual estimate of China’s holdings is difficult as China has been transferring some of its US Treasury bonds to third-party custodians such as Belgium (Euroclear) or Canada, in which case the value of these assets would be recorded under the name of the custodian country rather than China, meaning China's actual exposure may be higher than official data suggests. 

The U.S. Treasury Department itself acknowledges that if U.S. Treasury bonds purchased by foreign customers are held in custodial accounts in third countries, the true ownership will not be reflected in the data.  

Just last week, the financial website Bloomberg intimated that China had placed hundreds of billions of US Treasury bonds in Canada. According to Brad Setser, a senior fellow at the Council on Foreign Relations and former U.S. Treasury official, during the period when officially recorded Chinese holdings continued to decline, the U.S. Treasury holdings recorded under the names of Canada and Belgium rose abnormally. For example, Canada's holdings increased from $169 billion five years ago to $465 billion in August 2026, and Belgium's from $228 billion to $490.5 billion.

Rather than engaging in anti-hegemonic moves, China is advancing its own hegemonic interests. It is helping US imperialism, its economy and its foreign policy, by financing its trade deficit whilst looking for opportunities to promote alternatives to US dollar global trade. 

Xu Gao, Chief Economist of Bank of China International (China) Co., Ltd., wrote of China’s game plan back in June. He said, in words that will disappoint those who believe “China is leading an anti-hegemonic bloc”, that the priority for China should not be to overturn the dollar-centred system prematurely or to make renminbi internationalisation a bid to replace the dollar. It was not in China’s interests, he wrote, to overturn the dollar-centred system of international payments. He cautions that replacing the dollar with another sovereign currency would be extremely difficult.

Xu Gao believes that the most likely direction of change is a supranational currency supported by multiple sovereign currencies. It would work in a limited sphere and alongside the US dollar. China had proposed the R5 in October 2024, a currency for trade between the BRICS countries. However, this failed to eventuate when the US threatened that if the BRICS countries did not use the US dollar to trade, the US would impose heavy sanctions on those countries. India became the first country to back out of the BRICS currency concept in December 2024. That was a big setback because India is a major player in BRICS, and without India's participation, a common BRICS currency won't be possible.

China’s purchase of US Treasury bonds is part of the collusion vs contention paradigm that marks the relations between US imperialism and Chinese social-imperialism.  

Analysts concur that the bond market is in “meltdown”, that is, it is on the way to a systemic crisis. 

So long as public confidence in the bond markets can be sustained, a systemic crisis can be postponed. If confidence plunges through the inability of the US to maintain interest payments, or a sufficient number of countries use alternative payment arrangements to avoid the erratic imposition by the US of sanctions on countries using the dollar in their trade relations, then there may be a crisis that will include Australia in its impacts. 

Workers may be in for an even rougher time that at present.


Further reading: 

Xu Gao: The future of money, and China’s choices  

Bloomberg:  Talk grows that China is routing US Treasury holdings through Canada: 

Yahoo Finance: Global Bond Markets Are in Meltdown—Here’s Why U.S. Homebuyers Should Pay Attention  


Capitalist credit Pt 1: This little piggy went to market…

 Written by: Nick G. on 30 October 2026


Capital’s incessant drive to produce and accumulate more of itself relies on credit. 

Credit is a many-headed monster: credit cards, payday loans, consumer leases and rent-to-buy, bank and other financial institution loans, and the stock and bond markets.

In the first lot of credit, the consumer is the recipient; in the stock and bond markets, companies and governments are the recipients. 
 
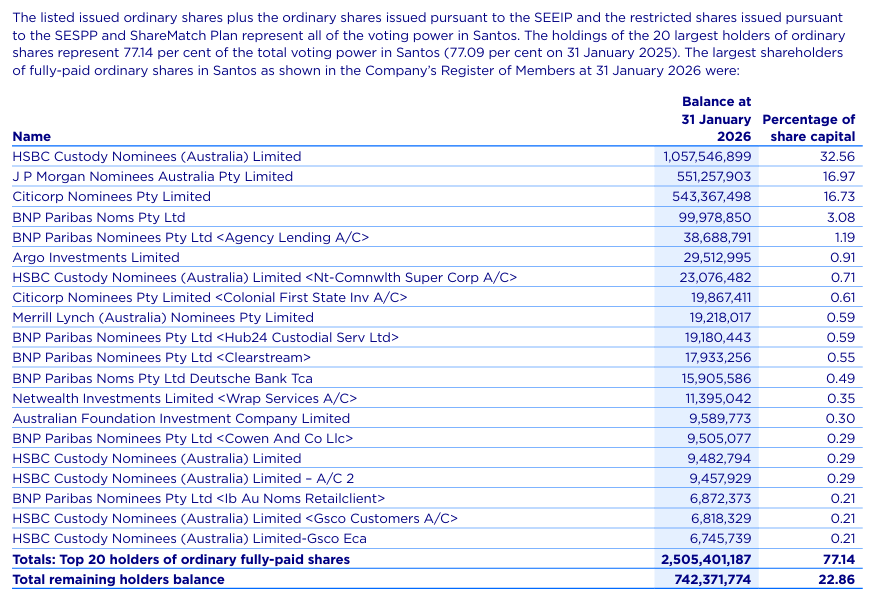
The little piggies who have gone to the stock market are the so-called “mum and dad” investors. Taking gas giant Santos as an example, there were 69,080 investors owning between 1 and 1,000 shares each. They held in total just 0.91 percent of Santos shares.
 
The big piggies that went to market are the institutional investors. These include hedge funds, mutual funds, pension funds, and insurance companies. They are the managers of other people’s money, but those “other people” are rarely mum and dad investors. They are usually large corporations and private equity companies whose identity, and hence, country of origin, is usually not known. In the case of Santos, (a serial tax avoider, having paid no tax on its Australian earnings over the last eleven years) they are the 20 largest shareholders, and those twenty hold just over 77 percent of Santos shares. 
 
 
Both the mum and dad investors and the institutional investors are extending credit to Santos by purchasing shares in the company. The value of those shares is market-driven – they can either rise or fall in price. The capital raised by these share purchases remains a fictional amount until such time as the profits from future surplus value creation allows the payment of a variable interest (dividends) to the shareholders. 
 
All of those shareholders are also gamblers, speculating on the shares holding or increasing their value along with the regular payment of dividends. A fall in the price of shares may occur in any company, but if it is a generalised fall then the stock market has crashed. If that fall particularly hits one type of company or industry, then the over-inflated value of those shares, their cost having greatly exceeded the ability of the industry to create enough surplus value, means that the bubble of over-investment has burst. Some are expecting there to be an AI bubble burst similar to the 2000-2002 dot.com bubble burst.
 
Of course, not every little piggy goes to market. Some stay at home.  They don’t eat roast beef and usually have none. Many are locked out through poverty and low wages. Rather than buying shares, they are counting the cost of their kids’ involvement in out-of-school sports, they are depending on Foodbank and other hunger relief charities, they are praying that they can keep a roof over their heads, they are keeping the cheapest available second- or third-hand cars on the road and paying Trumpian prices for their petrol, and the last thing they are hoping is that Santos continues to expand.
 
And if there is a bursting speculative bubble, or a general stock market crash, all those little piggies will go “wee, wee, wee” all the way home.
 
Next time: Their word is your bond
 
Further reading: 


Sunday, October 25, 2026

SA’s OZASIA Festival Scrapped

Written by: Ned K. on 26 October 2026


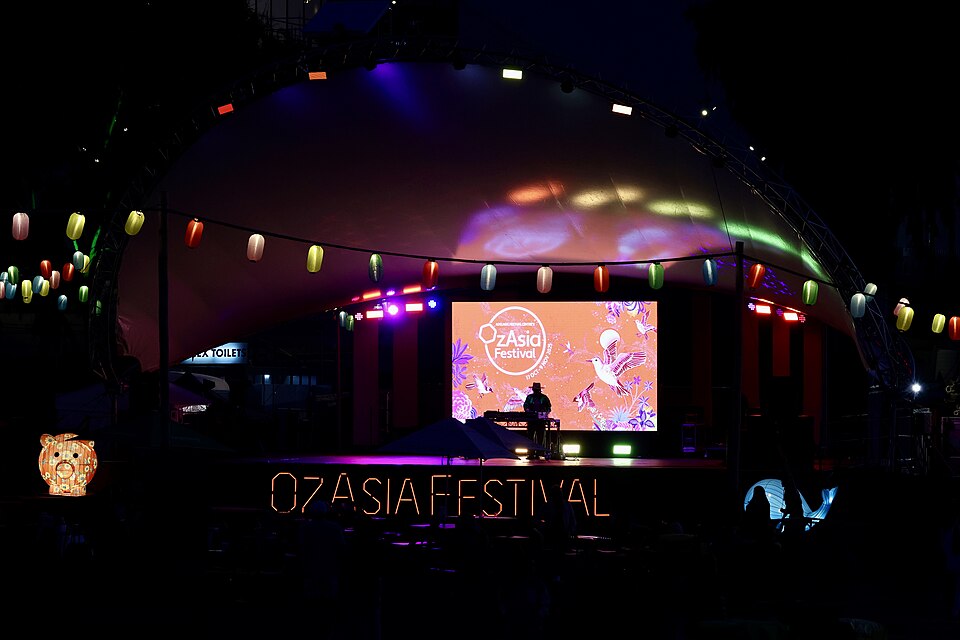
(Above: the 2025 OzAsia Festival, photo by Yu Chu Chin, Creative Commons Attribution-Share Alike 4.0)

The annual OzAsia Festival in Adelaide is being scrapped by the SA Government's Adelaide Festival Centre, despite Premier Malinauskas speaking about the importance of immigration from Asian countries to the well-being of the economy.

The festival has been held each October since 2007. October 2026 is its last year. Each year (apart from Covid years) it has attracted up to 200,000 people and has been recognised as Australia's leading contemporary arts festival engaging with Asia. It has included Asian and Australian music, visual arts, literature, a large variety of Asian food stalls and a writing and ideas program called Weekend of Words. Weekend of Words provided the opportunity for Asian Australian writers, journalists, artists, political analysts, comedians to discuss with their audiences Australia's engagement with Asia.

The SA Government funds the OzAsia Festival to the modest amount of $40,000 per year. This is a small portion of the SA Government's $250 million funding of the Arts which recently has included renovations of the Adelaide Festival Centre and $200 million to the Adelaide Fringe Festival.

The 200,000 people per year visiting the festival has included people of diverse cultural backgrounds. 

Danielle Lim, leader of Contemporary Asian Australian Performance said about the scrapping of OzAsia Festival, "If you want to ask an Asian artist where they started, I think it's very likely to hear OzAsia", according to an ABC report.

The end of the OzAsia Festival also includes the end of its Weekend of Words, one of the last remaining live forums led by Asian Australian writers, journalists, scientists and media workers.

The closing down of Weekend of Words follows the banning of a Palestinian Australian writer from presenting at the Adelaide Festival of Arts Writers Week last year on the urging of SA Premer Malinauskas, and the subsequent closure of the Writers Week when the vast majority of participants pulled out in solidarity with author Randa Abdel-Fattah.

These politically progressive festivals have been scrapped despite South Australia having had an ALP government since 2002 except for the four-year term of the Marshall Liberal government from 2018 to 2022.

More government money has been directed to other events such as Liv Golf, MotorGP and Gather Round (AFL games). The costs of these events has been hidden by the arboricidal Premier behind “commercial in confidence” provisions, but they run into the hundreds of millions, dwarfing the paltry tens of thousands spent to hold the OzAsia Festival.

The SA government's priorities regarding events may attract a temporary increase in profits for hospitality and accommodation sectors of the economy but do nothing to improve the living standards of working people and nothing to strengthen cultural diversity within the state.